Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
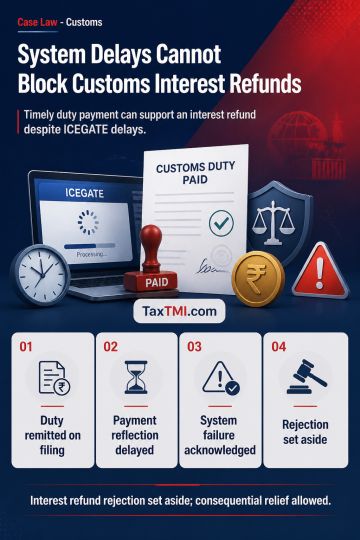
Customs interest arising solely because ICEGATE technical glitches prevented timely reflection of duty payment may be refundable where duty was remitted on the Bill of Entry filing date. The Tribunal treated the continued system failure, acknowledged up to 27 July 2023, as defeating a denial based only on filing the Bill of Entry after the waiver order's specified date. It set aside the rejection of the interest refund and allowed consequential relief according to law.
Customs interest arising solely because ICEGATE technical glitches prevented timely reflection of duty payment may be refundable where duty was remitted on the Bill of Entry filing date. The Tribunal treated the continued system failure, acknowledged up to 27 July 2023, as defeating a denial based only on filing the Bill of Entry after the waiver order's specified date. It set aside the rejection of the interest refund and allowed consequential relief according to law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913