GST offence classification determines whether arrest and bail restrictions apply, while continued custody requires an individualised necessity assessm...
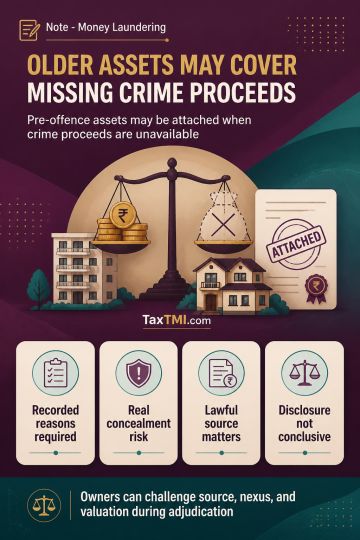
Under the PMLA, property acquired before a scheduled offence is not ordinarily directly derived from later criminal activity, but may be provisionally attached as the equivalent value of unavailable or dissipated proceeds of crime under the broader interpretation of the value limb. Attachment requires an identified scheduled offence, a reasoned assessment of illicit proceeds and equivalent value, and written reasons based on material showing a real risk that the property may be concealed, transferred or otherwise dealt with to frustrate confiscation. Income-tax disclosure is relevant but not conclusive. Statutory adjudication must allow the affected person to establish lawful source, challenge the asserted nexus and address valuation.
Under the PMLA, property acquired before a scheduled offence is not ordinarily directly derived from later criminal activity, but may be provisionally attached as the equivalent value of unavailable or dissipated proceeds of crime under the broader interpretation of the value limb. Attachment requires an identified scheduled offence, a reasoned assessment of illicit proceeds and equivalent value, and written reasons based on material showing a real risk that the property may be concealed, transferred or otherwise dealt with to frustrate confiscation. Income-tax disclosure is relevant but not conclusive. Statutory adjudication must allow the affected person to establish lawful source, challenge the asserted nexus and address valuation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI