Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
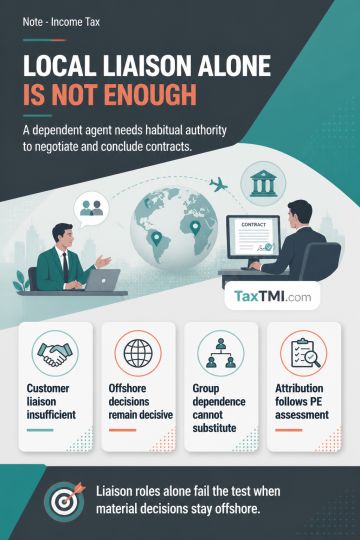
Dependent agent permanent establishment under Article 5(5) of the India-Switzerland DTAA requires cogent evidence that an Indian intermediary both has authority to negotiate and enter contracts for the foreign enterprise and habitually exercises that authority. Customer liaison, account management, administrative support, communicating pre-approved terms, and assisting an online contracting process do not satisfy that test where material commercial decisions remain offshore. Group control or economic dependence cannot replace the positive authority requirement, though they may affect independent-agent status. PE existence must be determined before Article 7 profit attribution; arm's-length remuneration does not itself prevent a DAPE, but may affect attribution if a PE exists. Rule 10 becomes relevant only where income cannot be definitely ascertained.
Dependent agent permanent establishment under Article 5(5) of the India-Switzerland DTAA requires cogent evidence that an Indian intermediary both has authority to negotiate and enter contracts for the foreign enterprise and habitually exercises that authority. Customer liaison, account management, administrative support, communicating pre-approved terms, and assisting an online contracting process do not satisfy that test where material commercial decisions remain offshore. Group control or economic dependence cannot replace the positive authority requirement, though they may affect independent-agent status. PE existence must be determined before Article 7 profit attribution; arm's-length remuneration does not itself prevent a DAPE, but may affect attribution if a PE exists. Rule 10 becomes relevant only where income cannot be definitely ascertained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915