Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
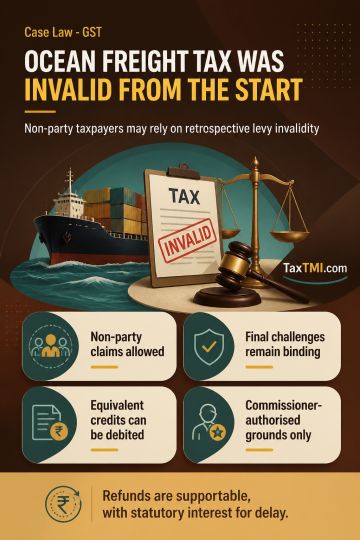
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
Page of 4918
Press 'Enter' after typing page number.
561 to 580 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Omission of clause (i) of section 92BA rendered transfer-pricing...
Omitted specified-domestic-transaction rules invalidated transfer-pricing adjustments, while derivative losses and exempt-income expenditure limits remained sustainable.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Omission of clause (i) of section 92BA rendered transfer-pricing references and consequential adjustments for covered specified domestic transactions unsustainable, making the alternative dispute over the most appropriate method academic. Mark-to-market losses from equity and currency futures remained allowable because no material factual or legal distinction from the earlier decision was established. Where audited statements showed own funds exceeded investments generating exempt income, no interest disallowance applied. Administrative expenditure disallowance was confined to investments relevant to exempt income after crediting the taxpayer's self-disallowance. The Revenue's appeals were dismissed, while the taxpayer's alternate challenge did not survive.
Omission of clause (i) of section 92BA rendered transfer-pricing references and consequential adjustments for covered specified domestic transactions unsustainable, making the alternative dispute over the most appropriate method academic. Mark-to-market losses from equity and currency futures remained allowable because no material factual or legal distinction from the earlier decision was established. Where audited statements showed own funds exceeded investments generating exempt income, no interest disallowance applied. Administrative expenditure disallowance was confined to investments relevant to exempt income after crediting the taxpayer's self-disallowance. The Revenue's appeals were dismissed, while the taxpayer's alternate challenge did not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918