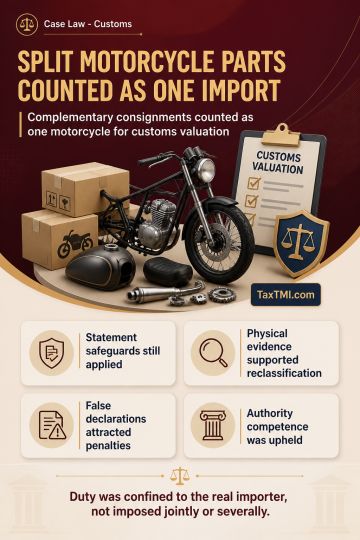
Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Omission of clause (i) of section 92BA rendered transfer-pricing...
Omitted specified-domestic-transaction rules invalidated transfer-pricing adjustments, while derivative losses and exempt-income expenditure limits remained sustainable.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Omission of clause (i) of section 92BA rendered transfer-pricing references and consequential adjustments for covered specified domestic transactions unsustainable, making the alternative dispute over the most appropriate method academic. Mark-to-market losses from equity and currency futures remained allowable because no material factual or legal distinction from the earlier decision was established. Where audited statements showed own funds exceeded investments generating exempt income, no interest disallowance applied. Administrative expenditure disallowance was confined to investments relevant to exempt income after crediting the taxpayer's self-disallowance. The Revenue's appeals were dismissed, while the taxpayer's alternate challenge did not survive.
Omission of clause (i) of section 92BA rendered transfer-pricing references and consequential adjustments for covered specified domestic transactions unsustainable, making the alternative dispute over the most appropriate method academic. Mark-to-market losses from equity and currency futures remained allowable because no material factual or legal distinction from the earlier decision was established. Where audited statements showed own funds exceeded investments generating exempt income, no interest disallowance applied. Administrative expenditure disallowance was confined to investments relevant to exempt income after crediting the taxpayer's self-disallowance. The Revenue's appeals were dismissed, while the taxpayer's alternate challenge did not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913