Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
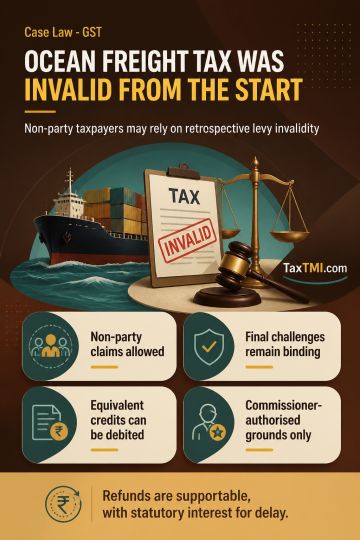
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Page of 4915
Press 'Enter' after typing page number.
501 to 520 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Cross-segment price manipulation may arise where futures orders...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, consent, connivance, or neglect.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Cross-segment price manipulation may arise where futures orders are allegedly used to move prices or create artificial order-book signals so that larger, economically opposite options positions obtain favourable execution. Section 12A of the SEBI Act and Regulations 3 and 4 of the PFUTP Regulations prohibit manipulative or deceptive devices, false appearances of trading and price manipulation; liability depends on the integrated sequence of orders, price impact, options execution, cancellations, exposure and persistence, rather than opposite positions or LTP contribution alone. Section 27 attributes company contraventions to directors responsible for business conduct, subject to knowledge and due-diligence defences, and separately covers consent, connivance or neglect. Interim measures may restrict market access, impound proceeds and preserve assets; disgorgement is generally person-specific, though joint-and-several exposure may follow common intentional action or a central role.
Cross-segment price manipulation may arise where futures orders are allegedly used to move prices or create artificial order-book signals so that larger, economically opposite options positions obtain favourable execution. Section 12A of the SEBI Act and Regulations 3 and 4 of the PFUTP Regulations prohibit manipulative or deceptive devices, false appearances of trading and price manipulation; liability depends on the integrated sequence of orders, price impact, options execution, cancellations, exposure and persistence, rather than opposite positions or LTP contribution alone. Section 27 attributes company contraventions to directors responsible for business conduct, subject to knowledge and due-diligence defences, and separately covers consent, connivance or neglect. Interim measures may restrict market access, impound proceeds and preserve assets; disgorgement is generally person-specific, though joint-and-several exposure may follow common intentional action or a central role.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915