Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
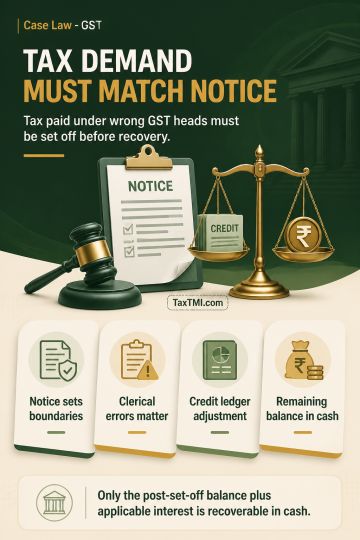
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918