Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Page of 4918
Press 'Enter' after typing page number.
641 to 660 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
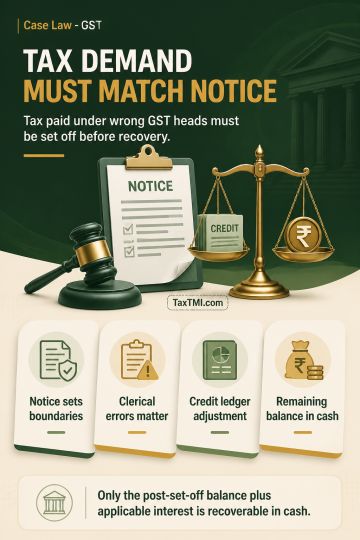
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918