TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
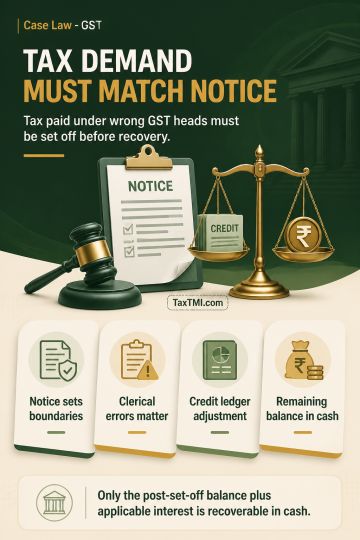
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Adjudication cannot sustain an alleged IGST short-payment demand on input-tax-credit eligibility grounds absent from the show-cause notice, particularly where the explanation for payment under different GST heads remains unaddressed. Payment of CGST and SGST instead of IGST because of a clerical error constitutes wrong-head payment rather than non-payment or short payment. Excess CGST and SGST credit should be set off against the IGST liability through the electronic credit ledger, with only any balance remaining after set-off recoverable in cash together with applicable interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918