Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
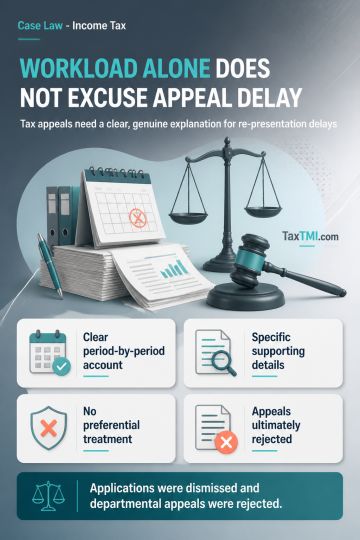
Condonation of extraordinary delay in re-presenting departmental tax appeals requires a reasonable, plausible and bona fide explanation supported by a coherent account of the period of inaction. General assertions of administrative workload, simultaneous appeal filings, voluminous records and procedural requirements do not establish sufficient cause. Delay in re-presentation is assessed less rigorously than delay under the Limitation Act, but government departments receive no preferential treatment and must show diligence and bona fide effort. The condonation applications were dismissed, and the departmental appeals were rejected.
Condonation of extraordinary delay in re-presenting departmental tax appeals requires a reasonable, plausible and bona fide explanation supported by a coherent account of the period of inaction. General assertions of administrative workload, simultaneous appeal filings, voluminous records and procedural requirements do not establish sufficient cause. Delay in re-presentation is assessed less rigorously than delay under the Limitation Act, but government departments receive no preferential treatment and must show diligence and bona fide effort. The condonation applications were dismissed, and the departmental appeals were rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918