Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
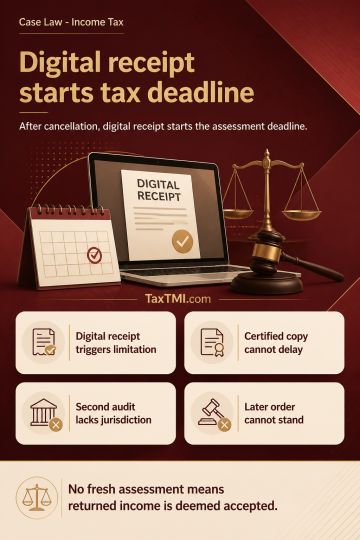
Limitation for completing an assessment after a special-audit direction is set aside runs until receipt of the judicial order, without requiring a certified copy where a digitally signed copy has been emailed or faxed to departmental authorities. Departmental receipt of the digitally signed order triggers the limitation period, and later production of a certified copy cannot postpone it. Where the assessment limitation expires before a second special-audit direction, that direction and its consequential audit report lack jurisdiction. Failure to complete the permissible fresh assessment results in deemed acceptance of the returned income, and no valid assessment order may thereafter be passed.
Limitation for completing an assessment after a special-audit direction is set aside runs until receipt of the judicial order, without requiring a certified copy where a digitally signed copy has been emailed or faxed to departmental authorities. Departmental receipt of the digitally signed order triggers the limitation period, and later production of a certified copy cannot postpone it. Where the assessment limitation expires before a second special-audit direction, that direction and its consequential audit report lack jurisdiction. Failure to complete the permissible fresh assessment results in deemed acceptance of the returned income, and no valid assessment order may thereafter be passed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899