Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
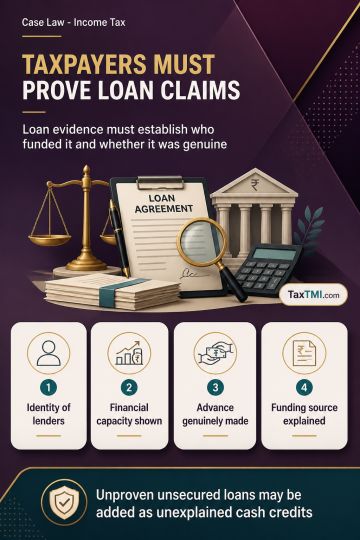
Section 68 places the initial burden on an assessee to establish, through cogent evidence, each loan creditor's identity, financial capacity and the genuineness of the transaction. Unsecured loans may be treated as unexplained cash credits where creditors deny making advances or cannot explain the source of the funds advanced, demonstrating that their creditworthiness has not been established. Failure to discharge this burden supports an addition for unexplained cash credits.
Section 68 places the initial burden on an assessee to establish, through cogent evidence, each loan creditor's identity, financial capacity and the genuineness of the transaction. Unsecured loans may be treated as unexplained cash credits where creditors deny making advances or cannot explain the source of the funds advanced, demonstrating that their creditworthiness has not been established. Failure to discharge this burden supports an addition for unexplained cash credits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915