Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Page of 4916
Press 'Enter' after typing page number.
681 to 700 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
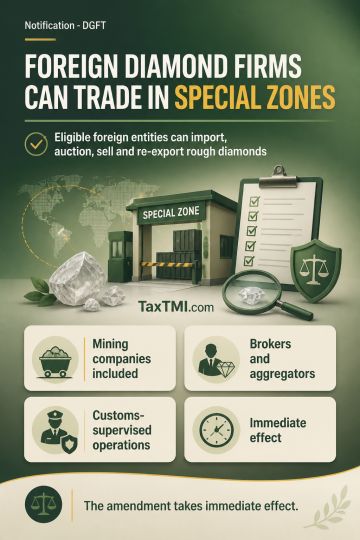
Paragraph 4.49 of FTP 2023 now permits eligible foreign entities to import rough diamonds into a Special Notified Zone and auction, sell or re-export them on a consignment or outright basis. Eligible entities include foreign diamond-mining companies, their sightholders, and brokers, aggregators, tender entities or auction entities connected with rough-diamond sales, where covered by and subject to conditions applicable under Entry 13F of Schedule IV to the Income-tax Act, 2025. SNZ operations remain administered by the SNZ operator under Customs supervision, and CBIC procedures govern import, auction, sale and re-export of unsold rough diamonds. The amendment takes immediate effect.
Paragraph 4.49 of FTP 2023 now permits eligible foreign entities to import rough diamonds into a Special Notified Zone and auction, sell or re-export them on a consignment or outright basis. Eligible entities include foreign diamond-mining companies, their sightholders, and brokers, aggregators, tender entities or auction entities connected with rough-diamond sales, where covered by and subject to conditions applicable under Entry 13F of Schedule IV to the Income-tax Act, 2025. SNZ operations remain administered by the SNZ operator under Customs supervision, and CBIC procedures govern import, auction, sale and re-export of unsold rough diamonds. The amendment takes immediate effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916