Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
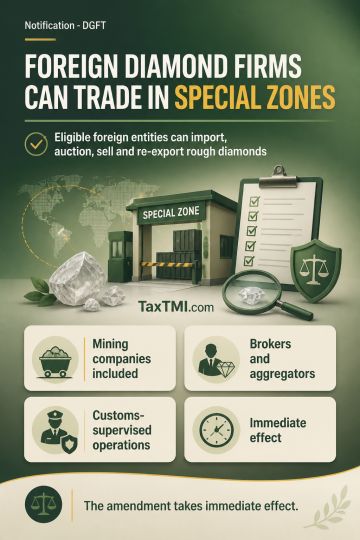
Paragraph 4.49 of FTP 2023 now permits eligible foreign entities to import rough diamonds into a Special Notified Zone and auction, sell or re-export them on a consignment or outright basis. Eligible entities include foreign diamond-mining companies, their sightholders, and brokers, aggregators, tender entities or auction entities connected with rough-diamond sales, where covered by and subject to conditions applicable under Entry 13F of Schedule IV to the Income-tax Act, 2025. SNZ operations remain administered by the SNZ operator under Customs supervision, and CBIC procedures govern import, auction, sale and re-export of unsold rough diamonds. The amendment takes immediate effect.
Paragraph 4.49 of FTP 2023 now permits eligible foreign entities to import rough diamonds into a Special Notified Zone and auction, sell or re-export them on a consignment or outright basis. Eligible entities include foreign diamond-mining companies, their sightholders, and brokers, aggregators, tender entities or auction entities connected with rough-diamond sales, where covered by and subject to conditions applicable under Entry 13F of Schedule IV to the Income-tax Act, 2025. SNZ operations remain administered by the SNZ operator under Customs supervision, and CBIC procedures govern import, auction, sale and re-export of unsold rough diamonds. The amendment takes immediate effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916