TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
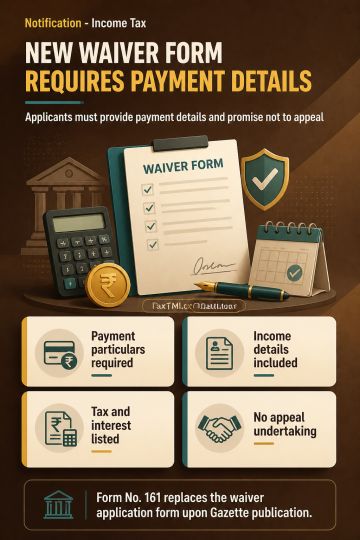
The Income-tax (Sixth Amendment) Rules, 2026 amend rule 231 to cover applications seeking waiver, as well as imposition, of penalty and substitute Form No. 161 for waiver applications. The prescribed form requires taxpayer and assessment or reassessment details, assessed and under-reported income, tax and interest payable, additional income-tax payable in lieu of penalty, and payment particulars. Additional income-tax is computed at 100% or 120% of tax on specified under-reported income categories. Applicants must verify that no appeal has been filed against the relevant order and undertake not to file one within the statutory period. The rules take effect upon Official Gazette publication.
The Income-tax (Sixth Amendment) Rules, 2026 amend rule 231 to cover applications seeking waiver, as well as imposition, of penalty and substitute Form No. 161 for waiver applications. The prescribed form requires taxpayer and assessment or reassessment details, assessed and under-reported income, tax and interest payable, additional income-tax payable in lieu of penalty, and payment particulars. Additional income-tax is computed at 100% or 120% of tax on specified under-reported income categories. Applicants must verify that no appeal has been filed against the relevant order and undertake not to file one within the statutory period. The rules take effect upon Official Gazette publication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918