Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
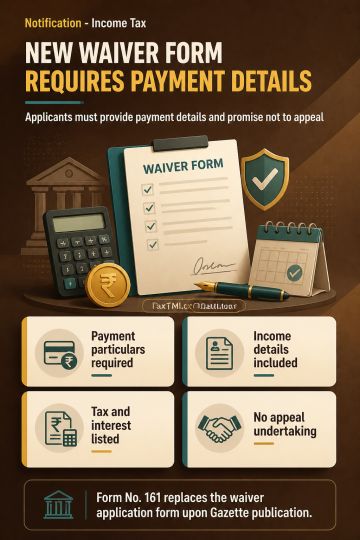
The Income-tax (Sixth Amendment) Rules, 2026 amend rule 231 to cover applications seeking waiver, as well as imposition, of penalty and substitute Form No. 161 for waiver applications. The prescribed form requires taxpayer and assessment or reassessment details, assessed and under-reported income, tax and interest payable, additional income-tax payable in lieu of penalty, and payment particulars. Additional income-tax is computed at 100% or 120% of tax on specified under-reported income categories. Applicants must verify that no appeal has been filed against the relevant order and undertake not to file one within the statutory period. The rules take effect upon Official Gazette publication.
The Income-tax (Sixth Amendment) Rules, 2026 amend rule 231 to cover applications seeking waiver, as well as imposition, of penalty and substitute Form No. 161 for waiver applications. The prescribed form requires taxpayer and assessment or reassessment details, assessed and under-reported income, tax and interest payable, additional income-tax payable in lieu of penalty, and payment particulars. Additional income-tax is computed at 100% or 120% of tax on specified under-reported income categories. Applicants must verify that no appeal has been filed against the relevant order and undertake not to file one within the statutory period. The rules take effect upon Official Gazette publication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915