Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
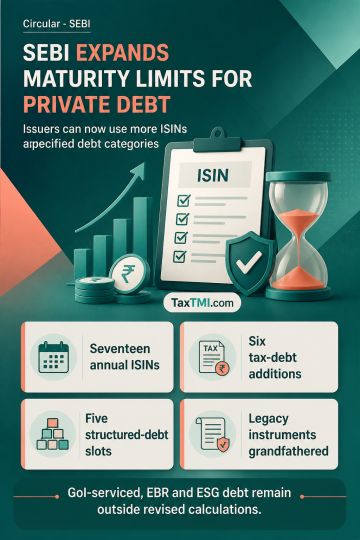
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899