Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
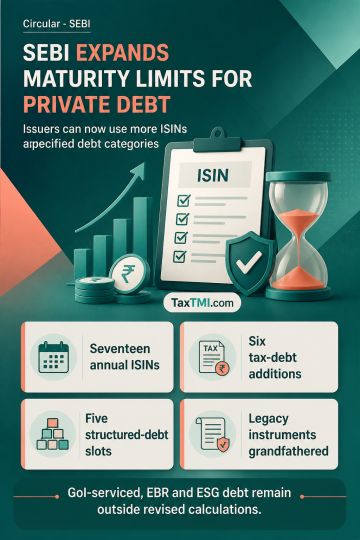
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923