Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
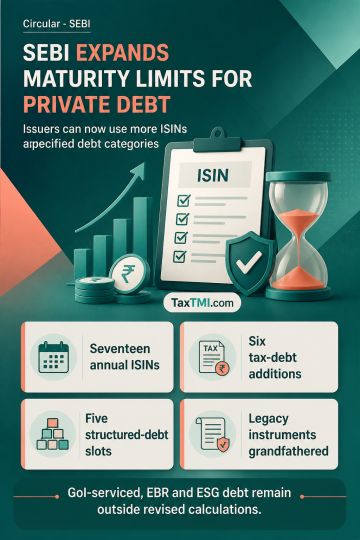
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
SEBI has revised ISIN limits for privately placed debt securities with immediate effect. Issuers may have up to seventeen ISINs maturing in a financial year, plus six additional ISINs for eligible capital gains tax debt securities. Of the seventeen, up to twelve may be plain vanilla debt securities, with additional ISINs permitted for prescribed incremental issuances after outstanding maturities exceed the specified threshold; up to five may cover structured, market-linked, floating-rate, zero-coupon and Tier II debt instruments. Legacy ISINs in the latter category are grandfathered subject to restrictions on further issuances. GoI-serviced/EBR bonds and ESG debt securities are excluded from ISIN-limit calculations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI