Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
Page of 4920
Press 'Enter' after typing page number.
421 to 440 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
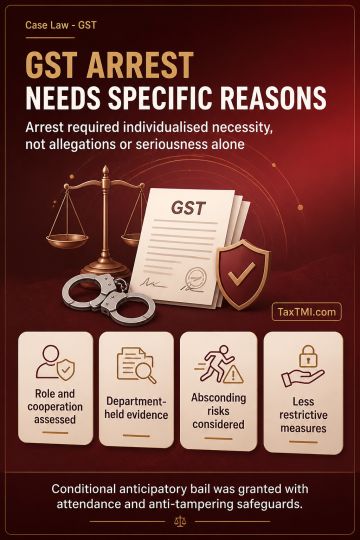
Custodial interrogation in alleged fraudulent GST input tax credit cases requires a specific, individualised showing of necessity. The seriousness or non-bailable character of an economic offence and statutory arrest powers alone do not justify arrest. Necessity must be assessed against the accused's role and cooperation, outstanding material, risks of absconding or evidence tampering, and whether less restrictive measures can meet investigative needs. Where documentary and electronic material has been seized and is already held by the Department, a bare assertion of necessity is insufficient. Anticipatory bail was granted subject to surrender, attendance, continued cooperation, and safeguards against absconding or tampering.
Custodial interrogation in alleged fraudulent GST input tax credit cases requires a specific, individualised showing of necessity. The seriousness or non-bailable character of an economic offence and statutory arrest powers alone do not justify arrest. Necessity must be assessed against the accused's role and cooperation, outstanding material, risks of absconding or evidence tampering, and whether less restrictive measures can meet investigative needs. Where documentary and electronic material has been seized and is already held by the Department, a bare assertion of necessity is insufficient. Anticipatory bail was granted subject to surrender, attendance, continued cooperation, and safeguards against absconding or tampering.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920