Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4918
Press 'Enter' after typing page number.
661 to 680 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
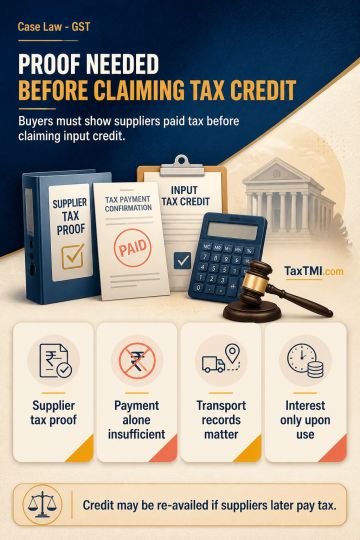
Input tax credit requires the recipient to establish that the supplier has paid tax to the Government; payment to the supplier alone is insufficient. A GSTR-2A shortfall does not itself establish non-payment, but the recipient must provide prescribed supplier certification or other evidence of tax payment. For inter-State purchases, an e-way bill is primary evidence of goods movement, and its absence requires reliable contemporaneous transport, freight, receipt, or stock evidence. Interest applies only to credit wrongly availed and utilised and must be computed from the electronic credit ledger under Rule 88B(3). Statutory penalty for ineligible credit under Section 73 does not require fraud or intent to evade; re-availment remains possible if suppliers later pay tax.
Input tax credit requires the recipient to establish that the supplier has paid tax to the Government; payment to the supplier alone is insufficient. A GSTR-2A shortfall does not itself establish non-payment, but the recipient must provide prescribed supplier certification or other evidence of tax payment. For inter-State purchases, an e-way bill is primary evidence of goods movement, and its absence requires reliable contemporaneous transport, freight, receipt, or stock evidence. Interest applies only to credit wrongly availed and utilised and must be computed from the electronic credit ledger under Rule 88B(3). Statutory penalty for ineligible credit under Section 73 does not require fraud or intent to evade; re-availment remains possible if suppliers later pay tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918