Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
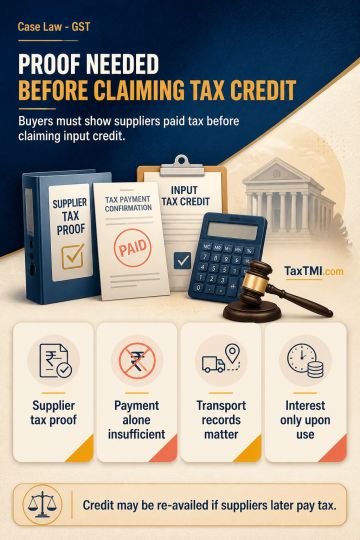
Input tax credit requires the recipient to establish that the supplier has paid tax to the Government; payment to the supplier alone is insufficient. A GSTR-2A shortfall does not itself establish non-payment, but the recipient must provide prescribed supplier certification or other evidence of tax payment. For inter-State purchases, an e-way bill is primary evidence of goods movement, and its absence requires reliable contemporaneous transport, freight, receipt, or stock evidence. Interest applies only to credit wrongly availed and utilised and must be computed from the electronic credit ledger under Rule 88B(3). Statutory penalty for ineligible credit under Section 73 does not require fraud or intent to evade; re-availment remains possible if suppliers later pay tax.
Input tax credit requires the recipient to establish that the supplier has paid tax to the Government; payment to the supplier alone is insufficient. A GSTR-2A shortfall does not itself establish non-payment, but the recipient must provide prescribed supplier certification or other evidence of tax payment. For inter-State purchases, an e-way bill is primary evidence of goods movement, and its absence requires reliable contemporaneous transport, freight, receipt, or stock evidence. Interest applies only to credit wrongly availed and utilised and must be computed from the electronic credit ledger under Rule 88B(3). Statutory penalty for ineligible credit under Section 73 does not require fraud or intent to evade; re-availment remains possible if suppliers later pay tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918