Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
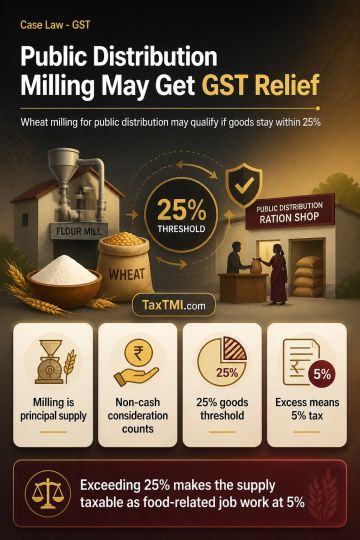
Composite supply of milling allocated wheat, fortifying the flour and packing it for Public Distribution System delivery has milling as its principal supply; fortification and packaging are ancillary. Total consideration includes cash and agreed non-cash consideration represented by retained gunny bags, bran and refractor, rather than their future disposal proceeds. Where goods used for fortification and packing remain within 25 per cent of total composite-supply value, the supply to the State Government qualifies for Serial No. 3A exemption because it relates to public distribution, a function under Article 243G. If the goods component exceeds that threshold, exemption is unavailable and the supply is taxable as food-related job work at 5 per cent.
Composite supply of milling allocated wheat, fortifying the flour and packing it for Public Distribution System delivery has milling as its principal supply; fortification and packaging are ancillary. Total consideration includes cash and agreed non-cash consideration represented by retained gunny bags, bran and refractor, rather than their future disposal proceeds. Where goods used for fortification and packing remain within 25 per cent of total composite-supply value, the supply to the State Government qualifies for Serial No. 3A exemption because it relates to public distribution, a function under Article 243G. If the goods component exceeds that threshold, exemption is unavailable and the supply is taxable as food-related job work at 5 per cent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915