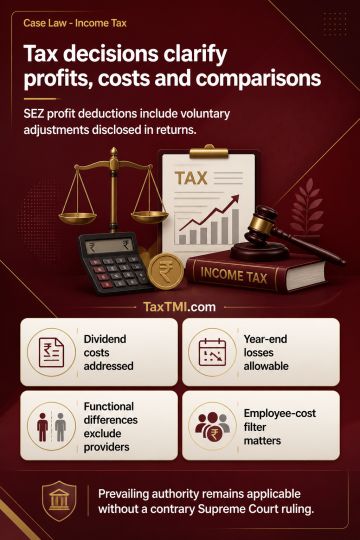
SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Delayed furnishing of a statement of financial transactions may attract penalty, but belated filing alone does not exclude the statutory defence of reasonable cause. Penalty should not be sustained without examining the taxpayer's explanation and supporting evidence for the delay. Where the first appellate authority has dismissed the matter without deciding the grounds on merits or considering reasonable cause, it should provide due opportunity, examine that defence, and determine the penalty afresh in accordance with law.
Delayed furnishing of a statement of financial transactions may attract penalty, but belated filing alone does not exclude the statutory defence of reasonable cause. Penalty should not be sustained without examining the taxpayer's explanation and supporting evidence for the delay. Where the first appellate authority has dismissed the matter without deciding the grounds on merits or considering reasonable cause, it should provide due opportunity, examine that defence, and determine the penalty afresh in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916