Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
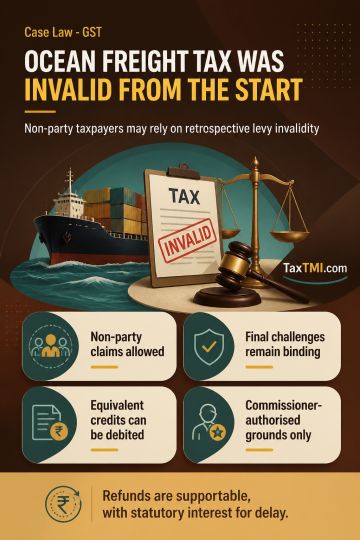
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
Page of 4918
Press 'Enter' after typing page number.
561 to 580 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Disputed valuation-based shareholder buy-out directions were stayed on an interim basis after the Appellate Tribunal found prima facie concerns that the valuation report relied on earlier reports already challenged. It also regarded a direction permitting share transfer either at the valuer-determined price or a mutually agreed price as controversial because both alternatives could not operate together. Directions to remove a director and appoint the minority shareholder's nominee director were retained, reflecting the shareholder's exclusion from meaningful participation in management; however, their implementation was deferred until the next listing. The impugned order therefore remains stayed except for those limited board-representation directions.
Disputed valuation-based shareholder buy-out directions were stayed on an interim basis after the Appellate Tribunal found prima facie concerns that the valuation report relied on earlier reports already challenged. It also regarded a direction permitting share transfer either at the valuer-determined price or a mutually agreed price as controversial because both alternatives could not operate together. Directions to remove a director and appoint the minority shareholder's nominee director were retained, reflecting the shareholder's exclusion from meaningful participation in management; however, their implementation was deferred until the next listing. The impugned order therefore remains stayed except for those limited board-representation directions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918