Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
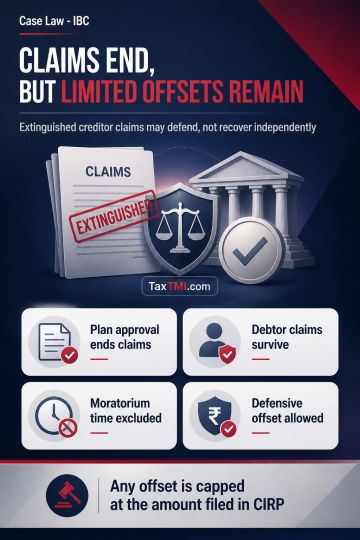
Under the IBC clean slate principle, approval of a resolution plan extinguishes claims against the corporate debtor and successful resolution applicant, including claims not lodged in CIRP, but preserves the corporate debtor's claims against its debtors. A former promoter's status as successful resolution applicant under the MSME exception does not change that effect. The CIRP moratorium is excluded when computing limitation for an arbitral claim arising from contract termination after CIRP commencement. An extinguished operational creditor's claim cannot support affirmative recovery but may be used as a defensive set-off against amounts payable on the corporate debtor's surviving claim, limited to the claim lodged in CIRP.
Under the IBC clean slate principle, approval of a resolution plan extinguishes claims against the corporate debtor and successful resolution applicant, including claims not lodged in CIRP, but preserves the corporate debtor's claims against its debtors. A former promoter's status as successful resolution applicant under the MSME exception does not change that effect. The CIRP moratorium is excluded when computing limitation for an arbitral claim arising from contract termination after CIRP commencement. An extinguished operational creditor's claim cannot support affirmative recovery but may be used as a defensive set-off against amounts payable on the corporate debtor's surviving claim, limited to the claim lodged in CIRP.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910