Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
Government road-restoration services for commercial pipeline work attract reverse-charge GST, while portal-issued proceedings remain valid without a p...
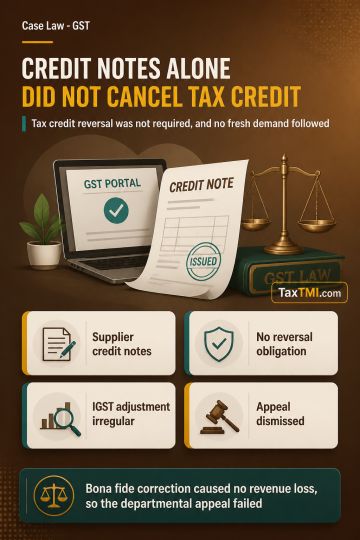
Recipient input tax credit did not require reversal solely because a supplier issued credit notes during the relevant period: neither the Act nor the Rules imposed that obligation, the statutory matching mechanism was inoperative, and Rule 37 concerned non-payment to suppliers. Accordingly, the premise for reversal failed. Excess IGST adjusted against CGST and SGST liabilities was procedurally irregular because the prescribed refund, re-credit or subsequent IGST-adjustment route was not used. However, as a bona fide first-year GST correction causing no revenue loss, it did not justify a fresh tax demand, interest or penalty; the departmental appeal was dismissed.
Recipient input tax credit did not require reversal solely because a supplier issued credit notes during the relevant period: neither the Act nor the Rules imposed that obligation, the statutory matching mechanism was inoperative, and Rule 37 concerned non-payment to suppliers. Accordingly, the premise for reversal failed. Excess IGST adjusted against CGST and SGST liabilities was procedurally irregular because the prescribed refund, re-credit or subsequent IGST-adjustment route was not used. However, as a bona fide first-year GST correction causing no revenue loss, it did not justify a fresh tax demand, interest or penalty; the departmental appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899