Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
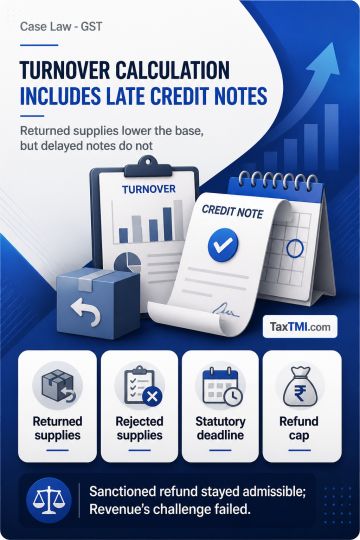
Credit notes validly issued for returned or rejected supplies reduce taxable turnover and are deductible from adjusted total turnover under the zero-rated supply refund formula. Credit notes issued during the refund period against invoices for Financial Year 2019-20 after expiry of the statutory time limit cannot be excluded from adjusted total turnover and must be included on recomputation. As the recomputed refund remained within the maximum permissible amount, the refund already sanctioned remained admissible and the Revenue challenge failed.
Credit notes validly issued for returned or rejected supplies reduce taxable turnover and are deductible from adjusted total turnover under the zero-rated supply refund formula. Credit notes issued during the refund period against invoices for Financial Year 2019-20 after expiry of the statutory time limit cannot be excluded from adjusted total turnover and must be included on recomputation. As the recomputed refund remained within the maximum permissible amount, the refund already sanctioned remained admissible and the Revenue challenge failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915