Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Page of 4912
Press 'Enter' after typing page number.
521 to 540 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
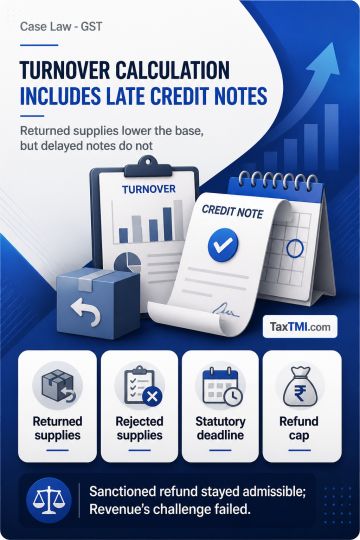
Credit notes validly issued for returned or rejected supplies reduce taxable turnover and are deductible from adjusted total turnover under the zero-rated supply refund formula. Credit notes issued during the refund period against invoices for Financial Year 2019-20 after expiry of the statutory time limit cannot be excluded from adjusted total turnover and must be included on recomputation. As the recomputed refund remained within the maximum permissible amount, the refund already sanctioned remained admissible and the Revenue challenge failed.
Credit notes validly issued for returned or rejected supplies reduce taxable turnover and are deductible from adjusted total turnover under the zero-rated supply refund formula. Credit notes issued during the refund period against invoices for Financial Year 2019-20 after expiry of the statutory time limit cannot be excluded from adjusted total turnover and must be included on recomputation. As the recomputed refund remained within the maximum permissible amount, the refund already sanctioned remained admissible and the Revenue challenge failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912