Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Page of 4918
Press 'Enter' after typing page number.
641 to 660 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
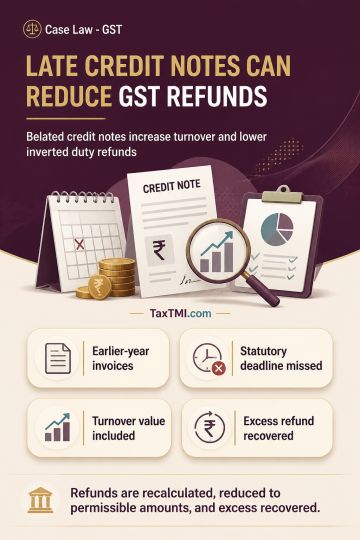
For inverted duty structure refunds, credit notes issued for returned or rejected supplies generally reduce taxable turnover and adjusted total turnover. Credit notes relating to invoices from an earlier financial year but issued after the statutory period for issuing and declaring them cannot be excluded from adjusted total turnover. Their value must therefore be included when recomputing accumulated input tax credit refund under Rule 89(5), reducing the refund to the permissible amount and requiring recovery of any excess refund.
For inverted duty structure refunds, credit notes issued for returned or rejected supplies generally reduce taxable turnover and adjusted total turnover. Credit notes relating to invoices from an earlier financial year but issued after the statutory period for issuing and declaring them cannot be excluded from adjusted total turnover. Their value must therefore be included when recomputing accumulated input tax credit refund under Rule 89(5), reducing the refund to the permissible amount and requiring recovery of any excess refund.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918