Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Page of 4902
Press 'Enter' after typing page number.
81 to 100 of 98028 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
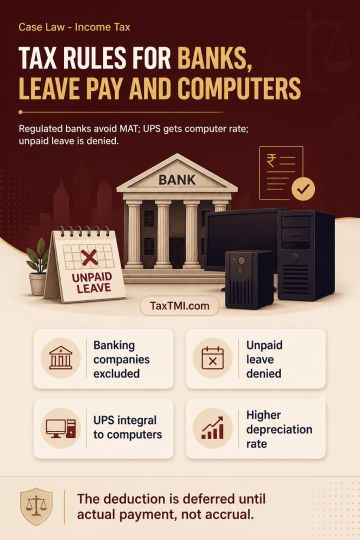
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902