Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
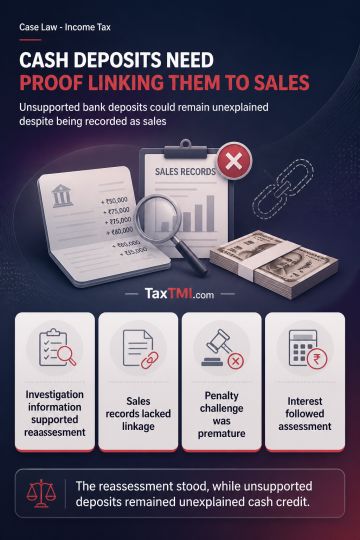
Reassessment initiated on specific Investigation Wing information about substantial cash deposits was sustained where the Assessing Officer examined the information and formed a belief that income had escaped assessment. Recording cash receipts as sales did not by itself establish that corresponding bank deposits arose from business sales; reliable linkage among the sales, stock movement and deposits was required to rebut an unexplained cash-credit addition. A challenge to mere initiation of penalty proceedings was premature, while interest levied consequentially on the assessment followed the assessment outcome.
Reassessment initiated on specific Investigation Wing information about substantial cash deposits was sustained where the Assessing Officer examined the information and formed a belief that income had escaped assessment. Recording cash receipts as sales did not by itself establish that corresponding bank deposits arose from business sales; reliable linkage among the sales, stock movement and deposits was required to rebut an unexplained cash-credit addition. A challenge to mere initiation of penalty proceedings was premature, while interest levied consequentially on the assessment followed the assessment outcome.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI