Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
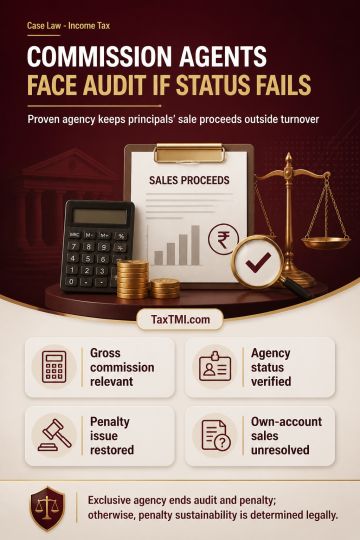
For a vegetable-market commission agent claiming status as a kachha arhtia, sale proceeds handled for principals do not constitute turnover for tax-audit purposes; gross commission alone is relevant under the CBDT Circular. Status must be verified because no conclusive material ruled out own-account purchases or sales. The penalty issue was restored for limited verification: proof of exclusive agency eliminates the audit obligation and penalty; otherwise, the penalty's sustainability must be determined in accordance with law.
For a vegetable-market commission agent claiming status as a kachha arhtia, sale proceeds handled for principals do not constitute turnover for tax-audit purposes; gross commission alone is relevant under the CBDT Circular. Status must be verified because no conclusive material ruled out own-account purchases or sales. The penalty issue was restored for limited verification: proof of exclusive agency eliminates the audit obligation and penalty; otherwise, the penalty's sustainability must be determined in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916