Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
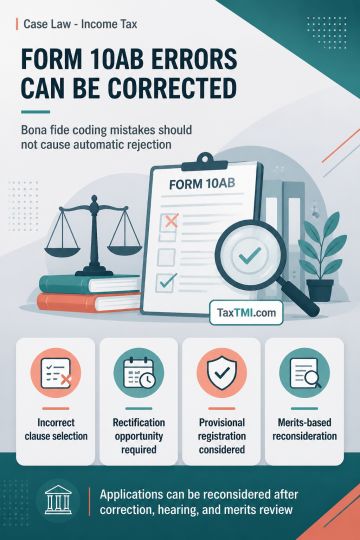
Incorrect selection of an applicable clause or code in Form 10AB for charitable registration or approval, when bona fide and inadvertent, warrants an opportunity for rectification rather than rejection solely on that technical ground. Where provisional registration has been granted on the same application, the technical error should not prevent consideration on merits. Applications may be reconsidered after correction of the form and a proper hearing, ensuring that procedural defects do not defeat substantive eligibility.
Incorrect selection of an applicable clause or code in Form 10AB for charitable registration or approval, when bona fide and inadvertent, warrants an opportunity for rectification rather than rejection solely on that technical ground. Where provisional registration has been granted on the same application, the technical error should not prevent consideration on merits. Applications may be reconsidered after correction of the form and a proper hearing, ensuring that procedural defects do not defeat substantive eligibility.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921