Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
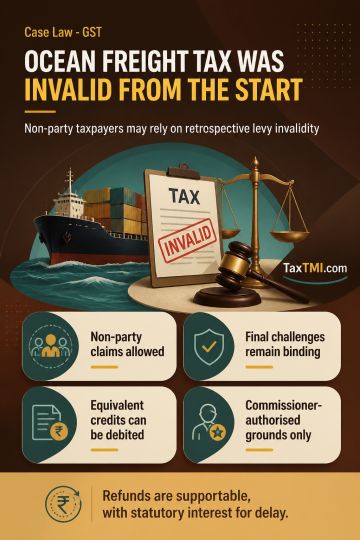
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
Page of 4918
Press 'Enter' after typing page number.
561 to 580 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Cash returned by builders from property payments made through banking channels constitutes circulation of explained funds, not unexplained money, unless evidence establishes a separate unexplained asset or accretion; the related addition was deleted. Alleged cash interest from builder financing was unsustainable where disclosed property investments, rent and capital gains supported appreciation rather than separate interest; that addition was deleted. Acquisition below stamp-duty value can attract section 56(2)(x)(b) irrespective of a transaction's builder-financing character, but disputed values require fair-market-value determination before taxability is decided; the issue was remanded. Set-off of brought-forward long-term capital loss was also remanded for verification of eligibility and the character of current-year capital gains.
Cash returned by builders from property payments made through banking channels constitutes circulation of explained funds, not unexplained money, unless evidence establishes a separate unexplained asset or accretion; the related addition was deleted. Alleged cash interest from builder financing was unsustainable where disclosed property investments, rent and capital gains supported appreciation rather than separate interest; that addition was deleted. Acquisition below stamp-duty value can attract section 56(2)(x)(b) irrespective of a transaction's builder-financing character, but disputed values require fair-market-value determination before taxability is decided; the issue was remanded. Set-off of brought-forward long-term capital loss was also remanded for verification of eligibility and the character of current-year capital gains.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918