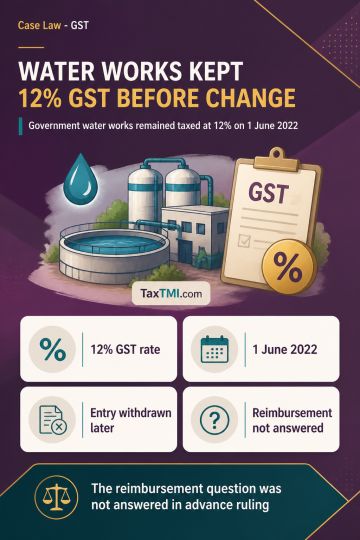
Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Under the Explanation to Rule 110(4) of the CGST Rules, an appeal is filed only upon issuance of the final acknowledgement. A mandatory pre-deposit made after provisional acknowledgement, but within the time allowed to rectify a defect and before final acknowledgement, satisfies the pre-deposit requirement under Section 112(8). The timing objection is therefore treated as cured, enabling registration and admission of the appeal for consideration on merits.
Under the Explanation to Rule 110(4) of the CGST Rules, an appeal is filed only upon issuance of the final acknowledgement. A mandatory pre-deposit made after provisional acknowledgement, but within the time allowed to rectify a defect and before final acknowledgement, satisfies the pre-deposit requirement under Section 112(8). The timing objection is therefore treated as cured, enabling registration and admission of the appeal for consideration on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916