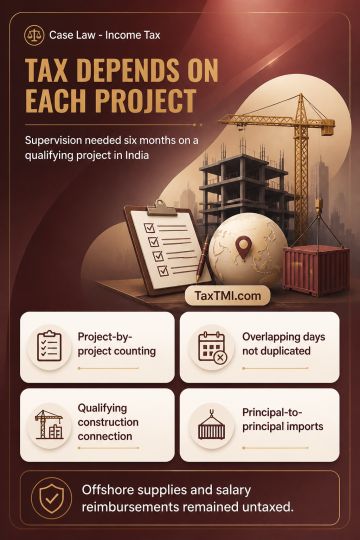
Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Page of 4916
Press 'Enter' after typing page number.
821 to 840 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Pecuniary jurisdiction limits under the applicable CBDT instruction required reassessment of a non-corporate assessee in a mofussil area exceeding the prescribed limit to be handled by an Assistant or Deputy Commissioner, rather than an Income-tax Officer. As the reassessment notice was issued by an officer lacking that jurisdiction and the defect was unrebutted, the notice was inherently invalid. The consequential assessment was quashed as void ab initio, rendering the remaining grounds academic.
Pecuniary jurisdiction limits under the applicable CBDT instruction required reassessment of a non-corporate assessee in a mofussil area exceeding the prescribed limit to be handled by an Assistant or Deputy Commissioner, rather than an Income-tax Officer. As the reassessment notice was issued by an officer lacking that jurisdiction and the defect was unrebutted, the notice was inherently invalid. The consequential assessment was quashed as void ab initio, rendering the remaining grounds academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916