Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Judicial declarations invalidating the reverse-charge IGST levy...
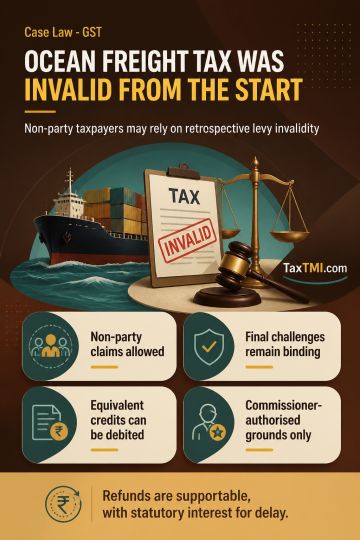
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal grounds.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial declarations invalidating the reverse-charge IGST levy on imported ocean freight operate retrospectively unless expressly limited, rendering the levy void from inception. Taxpayers who were not parties to the invalidating proceedings may rely on that declaration for refunds, except where their own unsuccessful challenge to the levy has attained finality. A departmental representative may challenge only grounds authorised by the Commissioner. Utilisation of IGST credit does not by itself create double benefit or unjust enrichment where unutilised CGST and SGST credits of equivalent value can be debited. Refunds are therefore supportable, with statutory interest for delay.
Judicial declarations invalidating the reverse-charge IGST levy on imported ocean freight operate retrospectively unless expressly limited, rendering the levy void from inception. Taxpayers who were not parties to the invalidating proceedings may rely on that declaration for refunds, except where their own unsuccessful challenge to the levy has attained finality. A departmental representative may challenge only grounds authorised by the Commissioner. Utilisation of IGST credit does not by itself create double benefit or unjust enrichment where unutilised CGST and SGST credits of equivalent value can be debited. Refunds are therefore supportable, with statutory interest for delay.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915