Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Revision of an income-tax intimation requires consideration of...
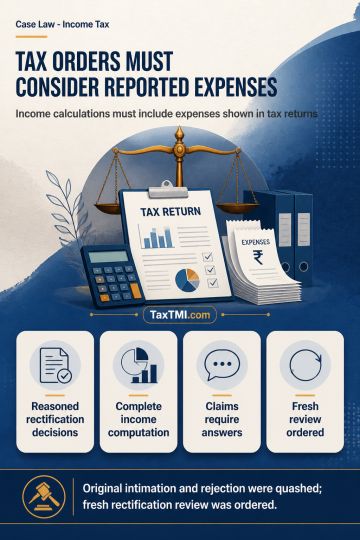
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income computation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Revision of an income-tax intimation requires consideration of expenditure disclosed in the return when computing income; overlooking that material indicates non-application of mind. The revision order was quashed because it proceeded on an incomplete computation. Rejection of a rectification application must be reasoned and address the taxpayer's claim. As the rejection communication and original intimation neither considered disclosed expenditure nor gave reasons, both were quashed. Fresh rectification was directed to be reconsidered after examining the return.
Revision of an income-tax intimation requires consideration of expenditure disclosed in the return when computing income; overlooking that material indicates non-application of mind. The revision order was quashed because it proceeded on an incomplete computation. Rejection of a rectification application must be reasoned and address the taxpayer's claim. As the rejection communication and original intimation neither considered disclosed expenditure nor gave reasons, both were quashed. Fresh rectification was directed to be reconsidered after examining the return.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915