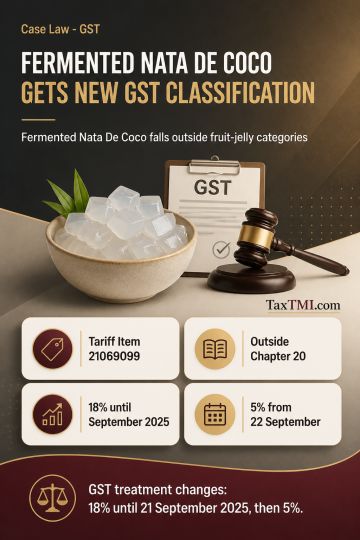
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Third-party loose sheets may trigger investigation but cannot,...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or ownership.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Third-party loose sheets may trigger investigation but cannot, without reliable evidence linking the assessee to the recorded transaction, prove unexplained expenditure. Presumptions attached to seized documents apply to the person from whose possession or control they are recovered; they do not establish the alleged payer, source or movement of funds. Actual incurrence is foundational, so an uncorroborated allegation cannot shift the burden of proof. Nor does a third-party reference establish ownership of unrecorded money; the statutory requirements for unexplained money and expenditure are distinct. These deficiencies made both additions unsustainable. Evaluation of material already on the assessment record does not amount to admitting additional evidence.
Third-party loose sheets may trigger investigation but cannot, without reliable evidence linking the assessee to the recorded transaction, prove unexplained expenditure. Presumptions attached to seized documents apply to the person from whose possession or control they are recovered; they do not establish the alleged payer, source or movement of funds. Actual incurrence is foundational, so an uncorroborated allegation cannot shift the burden of proof. Nor does a third-party reference establish ownership of unrecorded money; the statutory requirements for unexplained money and expenditure are distinct. These deficiencies made both additions unsustainable. Evaluation of material already on the assessment record does not amount to admitting additional evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913