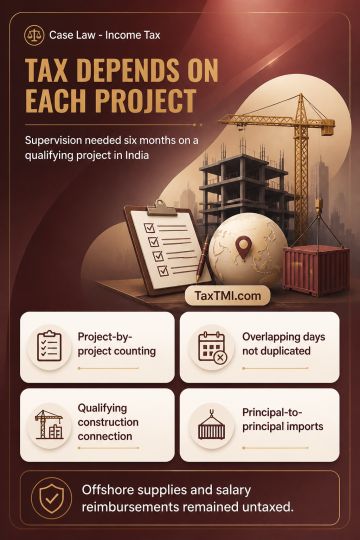
Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Page of 4916
Press 'Enter' after typing page number.
821 to 840 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Interest on wrongly availed and utilised input tax credit must be computed from the actual date of utilisation until the date of reversal. Section 50(3), read with rule 88B(3), does not permit interest to be calculated from an earlier date merely because the credit was wrongly availed. Where interest has been computed from an incorrect earlier date, the assessment order requires modification to apply the revised computation. Statutory appeal or revision remains available for any other disputed issue.
Interest on wrongly availed and utilised input tax credit must be computed from the actual date of utilisation until the date of reversal. Section 50(3), read with rule 88B(3), does not permit interest to be calculated from an earlier date merely because the credit was wrongly availed. Where interest has been computed from an incorrect earlier date, the assessment order requires modification to apply the revised computation. Statutory appeal or revision remains available for any other disputed issue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916