Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4912
Press 'Enter' after typing page number.
541 to 560 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
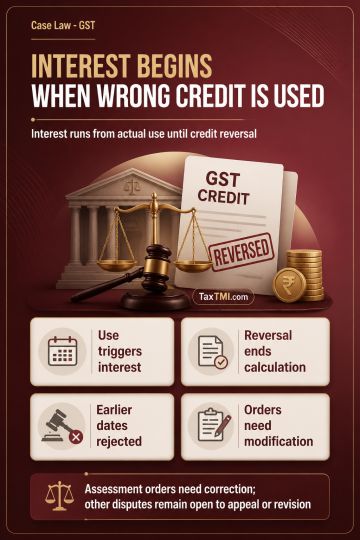
Interest on wrongly availed and utilised input tax credit must be computed from the actual date of utilisation until the date of reversal. Section 50(3), read with rule 88B(3), does not permit interest to be calculated from an earlier date merely because the credit was wrongly availed. Where interest has been computed from an incorrect earlier date, the assessment order requires modification to apply the revised computation. Statutory appeal or revision remains available for any other disputed issue.
Interest on wrongly availed and utilised input tax credit must be computed from the actual date of utilisation until the date of reversal. Section 50(3), read with rule 88B(3), does not permit interest to be calculated from an earlier date merely because the credit was wrongly availed. Where interest has been computed from an incorrect earlier date, the assessment order requires modification to apply the revised computation. Statutory appeal or revision remains available for any other disputed issue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912