Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
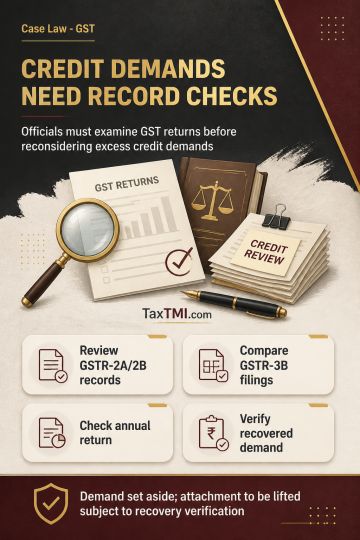
Input Tax Credit reconciliation through GSTR-2A/2B, GSTR-3B and the annual return may provide prima facie evidence of available credit. A tax demand alleging excess utilisation of Input Tax Credit requires reconsideration where those material records were not duly examined, with an opportunity to establish the credit claimed. Verification of asserted recovery of part of the demand is also required before releasing a bank attachment. The tax demand was set aside for fresh consideration, and the attachment was to be lifted subject to verification of recovery.
Input Tax Credit reconciliation through GSTR-2A/2B, GSTR-3B and the annual return may provide prima facie evidence of available credit. A tax demand alleging excess utilisation of Input Tax Credit requires reconsideration where those material records were not duly examined, with an opportunity to establish the credit claimed. Verification of asserted recovery of part of the demand is also required before releasing a bank attachment. The tax demand was set aside for fresh consideration, and the attachment was to be lifted subject to verification of recovery.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI