Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
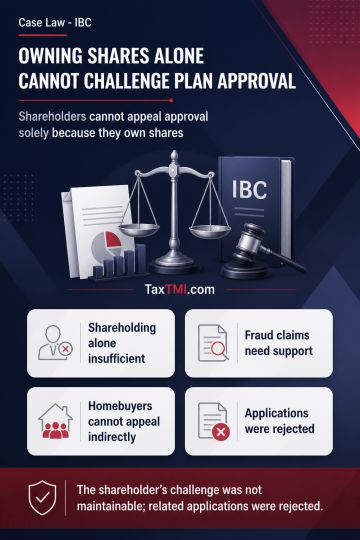
Individual shareholders do not, merely by virtue of shareholding, qualify as aggrieved persons entitled to appeal approval of a corporate debtor's resolution plan. Allegations that post-approval modifications were fraudulent cannot expand standing unless supported by specific material. Homebuyers who have not independently challenged the resolution plan cannot contest it indirectly by supporting a shareholder's appeal. The shareholder's challenge to the approved resolution plan was therefore treated as not maintainable, and the related interlocutory applications were rejected.
Individual shareholders do not, merely by virtue of shareholding, qualify as aggrieved persons entitled to appeal approval of a corporate debtor's resolution plan. Allegations that post-approval modifications were fraudulent cannot expand standing unless supported by specific material. Homebuyers who have not independently challenged the resolution plan cannot contest it indirectly by supporting a shareholder's appeal. The shareholder's challenge to the approved resolution plan was therefore treated as not maintainable, and the related interlocutory applications were rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905