Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
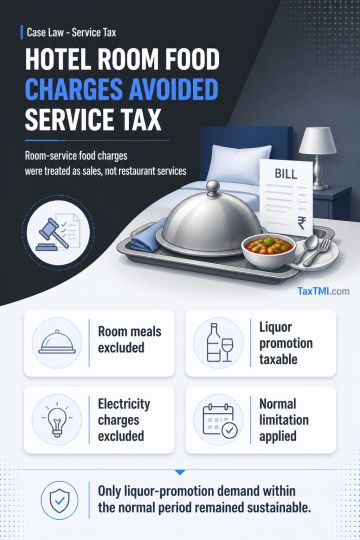
Separately billed room-service food and beverages supplied in hotel rooms were treated as sales rather than restaurant services because hotel rooms were not restaurant premises and no evidence linked the charges to room-service value; the related service-tax demand was set aside. Exclusive liquor-brand listing, displays and branded accessories constituted taxable promotional or sponsorship service, leaving that demand sustainable only within the normal limitation period. Actual electricity charges recovered from tenants on sub-meter readings and remitted to suppliers were not consideration for renting, so the demand was set aside. Extended limitation required deliberate evasion, not mere non-declaration; the surviving demand was restricted to the normal period.
Separately billed room-service food and beverages supplied in hotel rooms were treated as sales rather than restaurant services because hotel rooms were not restaurant premises and no evidence linked the charges to room-service value; the related service-tax demand was set aside. Exclusive liquor-brand listing, displays and branded accessories constituted taxable promotional or sponsorship service, leaving that demand sustainable only within the normal limitation period. Actual electricity charges recovered from tenants on sub-meter readings and remitted to suppliers were not consideration for renting, so the demand was set aside. Extended limitation required deliberate evasion, not mere non-declaration; the surviving demand was restricted to the normal period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905