Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
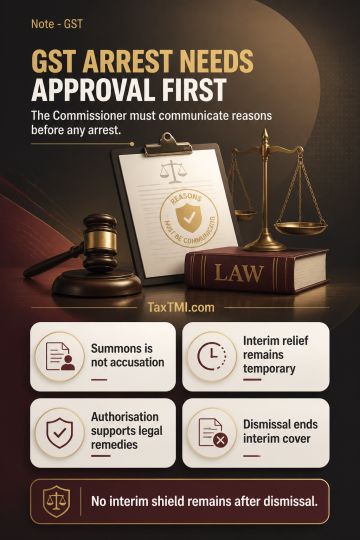
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902