Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Page of 4902
Press 'Enter' after typing page number.
241 to 260 of 98028 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
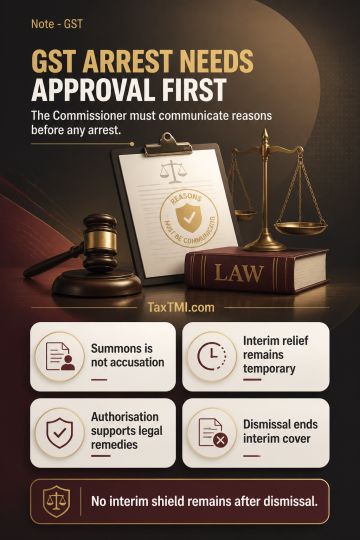
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902