Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Page of 4916
Press 'Enter' after typing page number.
681 to 700 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
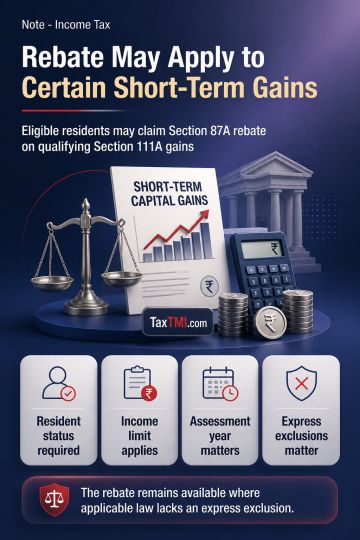
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916