Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
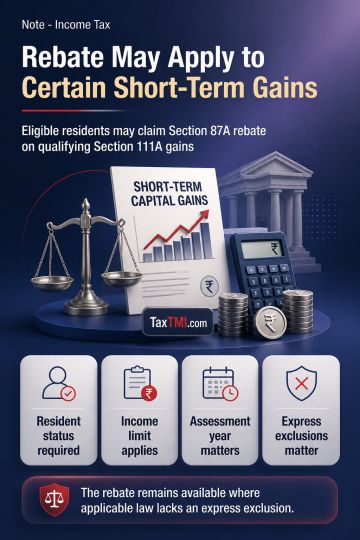
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910