Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
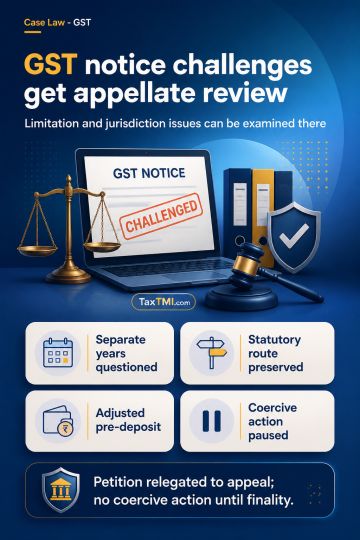
Availability of an efficacious statutory GST appeal generally weighs against writ adjudication of challenges to a consolidated show-cause notice. Objections that the notice is barred by limitation, issued without jurisdiction, or impermissibly combines separate financial years may involve disputed questions of fact and law suitable for appellate examination. The statutory appeal under Section 107 of the CGST Act preserves those objections for determination. The writ petition was relegated to that remedy, subject to an adjusted pre-deposit, with no coercive action until the appeal attains finality.
Availability of an efficacious statutory GST appeal generally weighs against writ adjudication of challenges to a consolidated show-cause notice. Objections that the notice is barred by limitation, issued without jurisdiction, or impermissibly combines separate financial years may involve disputed questions of fact and law suitable for appellate examination. The statutory appeal under Section 107 of the CGST Act preserves those objections for determination. The writ petition was relegated to that remedy, subject to an adjusted pre-deposit, with no coercive action until the appeal attains finality.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915